ESTIMASI NILAI WAJAR SAHAM PT CHANDRA DAYA INVESTASI TBK (CDIA) PASCA-IPO
Abstract
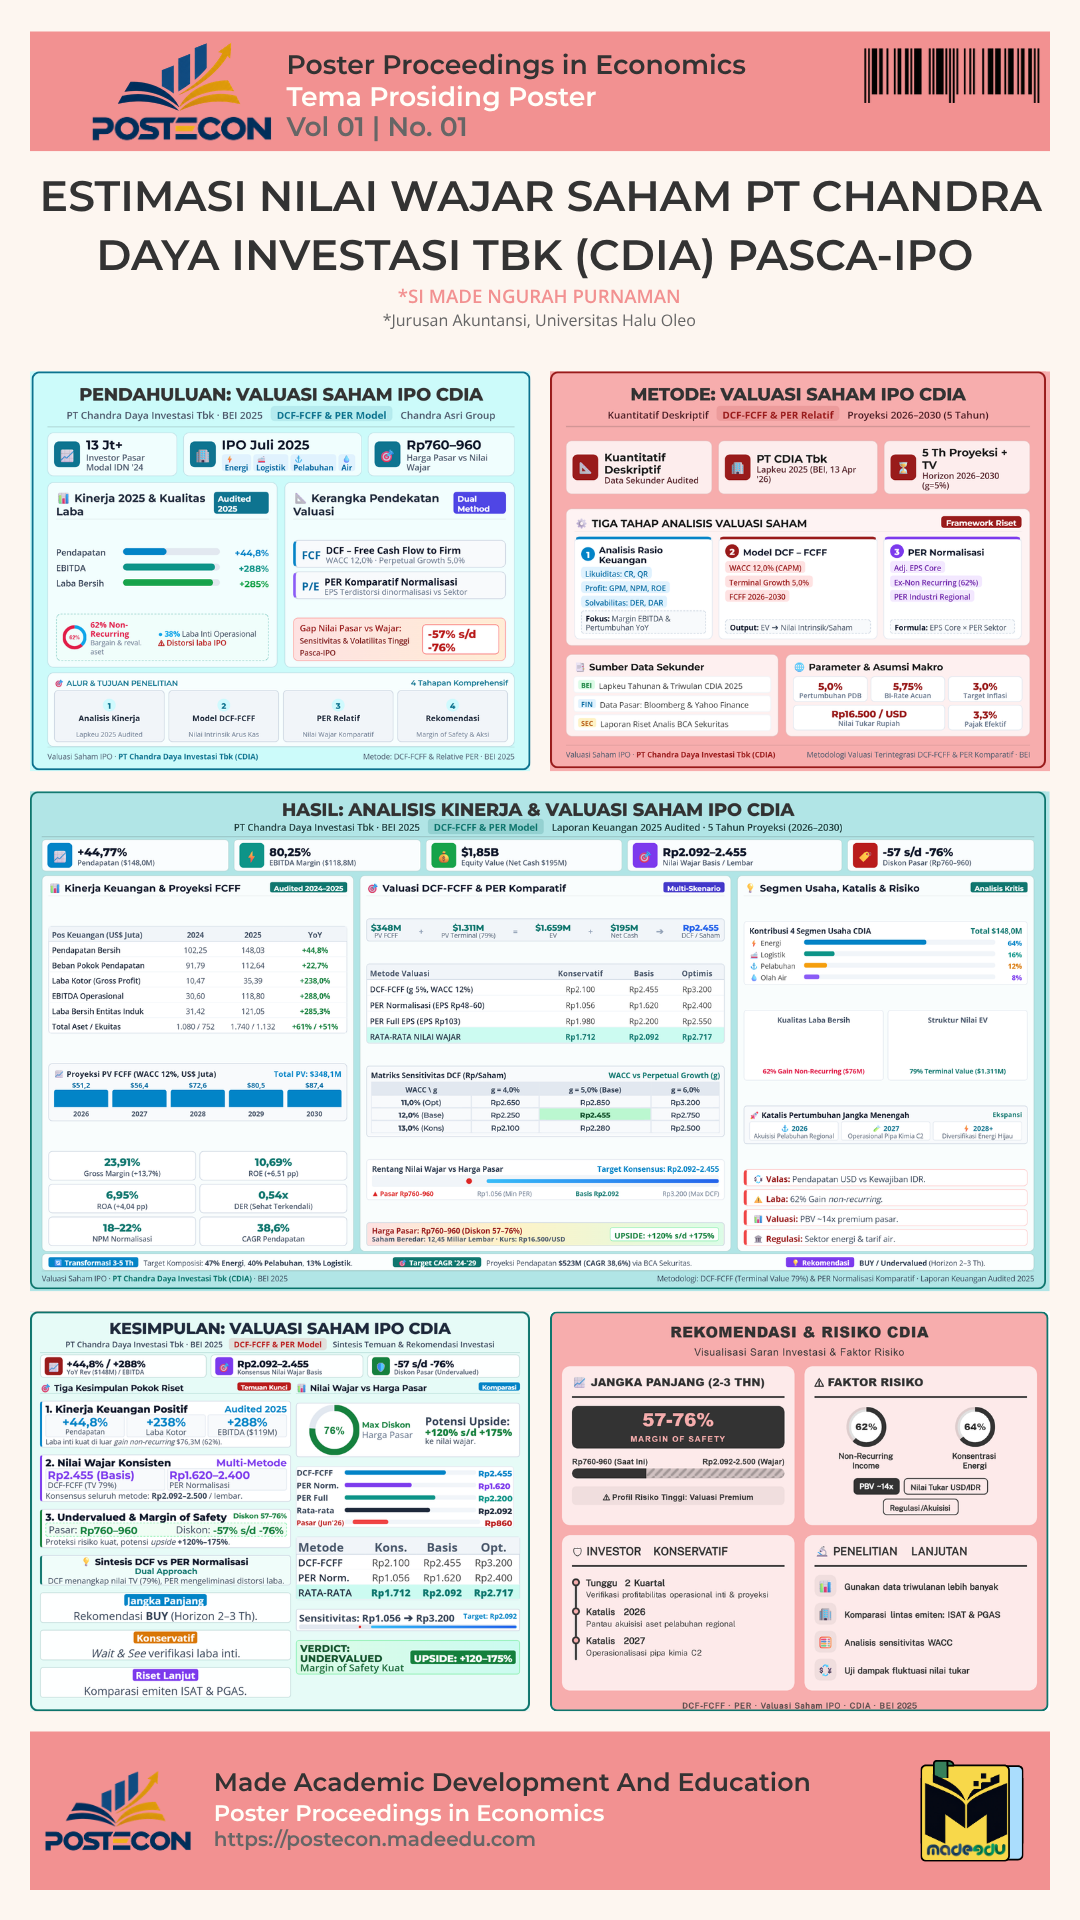
This study aims to estimate the fair value of PT Chandra Daya Investasi Tbk (CDIA) following its Initial Public Offering (IPO) using the Discounted Cash Flow-Free Cash Flow to Firm (DCF-FCFF) and Price Earnings Ratio (PER) methods. A descriptive quantitative approach was employed using secondary data obtained from the 2025 financial statements, stock price data, and supporting publications. The analysis included financial performance evaluation, intrinsic value estimation using DCF-FCFF, and relative valuation using PER. The results indicate that CDIA achieved revenue growth of 44.77%, EBITDA growth of 288%, and net income growth of 285.26%, although part of the earnings increase was driven by non-recurring items. The DCF-FCFF method estimated a fair value of approximately IDR2,455 per share, while the PER approach produced a fair value range of IDR1,620 to IDR2,400 per share. Compared with the June 2026 market price of IDR760 to IDR960 per share, CDIA appears to be undervalued, offering a potential upside of approximately 57% to 76%. These findings suggest that combining DCF-FCFF and PER provides a more comprehensive valuation framework and supports investment decisions based on fundamental analysis.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Poster Proceedings in Economics

This work is licensed under a Creative Commons Attribution-NonCommercial-ShareAlike 4.0 International License.